B9: Cash Advance
- 4.6
- Rating
- 1.00M
- Installs
- Free
- Price
 Analysis by App-foxy
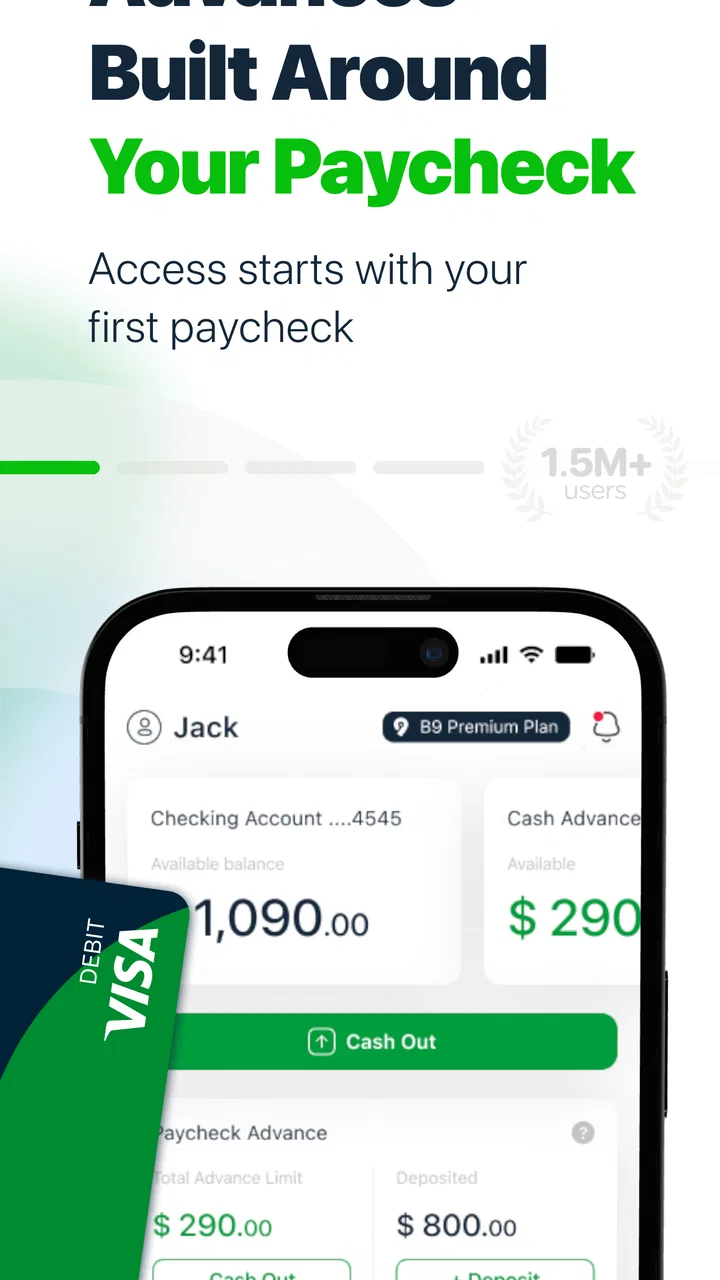
When a bill arrives before payday, the problem is rarely complicated: I know money is coming, but the timing is wrong. B9: Cash Advance is built around that exact gap, offering a way to request an advance from an upcoming paycheck through a free finance app. I approached it as a practical cash-flow tool rather than a general budgeting service, and that distinction matters from the first screen.
The app is developed by B9 - Get Your Paycheck Early and is available to an Everyone audience. It has passed the point of being a niche experiment, with over one million installs, a 3.9 average from around twelve thousand ratings, and roughly seven thousand reviews. Those figures suggest a service many people are actively trying, while also hinting that the experience may not feel equally smooth for every financial situation.
From a shortfall before payday to a completed advance
I start this section with the moment the need becomes concrete: a bill or essential purchase is due, while my paycheck is still on its way. I’ll look at how to keep that shortfall distinct from a wider budget problem, then follow the decisions that matter before an advance is complete. The key is to treat speed as useful only when the repayment plan is already clear.
You May Also Like

 Blood Strike: 2.5 Anniversary
Blood Strike’s Loadouts Turn Every Drop Into a Tactical Gamble
A close look at Blood Strike’s custom loadouts: how fast access to signature weapons reshapes its battle royale rhythm, rewards preparation, and narrows the gap between fights.

 Pandora - Music & Podcasts
Pandora’s Music Is Easy to Start, but Harder to Recover
Pandora’s strength is its low-effort path from a seed to a station. Its weak spot is how much confidence it asks you to place in connection, setup, and quiet recovery.

 8 Ball Pool
 Is Built on Rivalries, Rematches, and Routine
A close look at the rivalries, rematches, shared routines, and unanswered safety questions that turn a quick pool match into a persistent mobile community.

 Samsung Music
’s Quiet Strength Is Playing What You Already Own
Its reach comes less from spectacle than from dependable access to a personal library. That simplicity is both the app’s strongest retention engine and its ceiling.

 AccuWeather: Weather Radar
AccuWeather Review: A Quick, Clear Forecast for Everyday Decisions
For everyday plans, the best forecast is the one you can understand quickly. AccuWeather makes rain timing, radar, and local conditions easy to act on, with a few trade-offs.

 Hill Climb Racing
Why Hill Climb Racing Still Turns Crashes Into One More Run
A tiny car, a bumpy hill and one more upgrade: Hill Climb Racing keeps resurfacing because its simple chaos makes every near-miss feel personal.
More From Our News Desk



Starting with the actual cash-flow problem
I would start by asking a simple question: is this a one-time timing issue, or am I regularly spending more than my income can support? B9 is much more sensible for the first situation. If rent, transport, groceries, or an unexpected household expense lands a few days before income arrives, an advance can potentially bridge the gap. It is less suitable as a permanent answer to a recurring deficit.
That first distinction prevents a common mistake. An early paycheck does not create extra income; it changes when part of that income becomes available. I would therefore look at the next payday, the amount already committed to bills, and what must remain available afterward before requesting anything. The app can help with timing, but it cannot make an unaffordable month affordable.
The app is free to download, which makes trying the initial experience relatively accessible. Still, “free” should not be treated as a promise that every aspect of an advance has no cost. Before accepting an offer, I would read the displayed terms carefully, including any repayment details or charges shown during the process. That small pause is more important than the convenience of reaching the request screen quickly.
Setting up the information the service needs
The next stage is the practical handoff between me and the service: I provide the information required to understand my income situation, and the app uses that information to determine whether an advance can be offered. This is where expectations should stay realistic. Downloading the app does not automatically mean that every user receives the same result or amount.
I would complete the setup slowly rather than rushing through it just to see the home screen. Financial apps are not the place for guesses, mismatched details, or an old account that no longer receives income. If the information connected to the request does not reflect my current situation, the process may become confusing or stop before an advance is available.
This is also the point where privacy deserves attention. I would review each permission and connection request in context, especially when linking information related to earnings or an account. My rule is straightforward: if I do not understand why a piece of information is needed, I do not proceed until I have read the explanation in the app. Convenience is useful, but financial access should never be automatic in my mind.
Reviewing the advance before accepting it
Once an offer or advance path appears, I would treat the review screen as the most important part of the workflow. I would check how much is being advanced, when repayment is expected, and what the transaction means for the next payday. The useful comparison is not “Can I get this money now?” but “What will my account look like after this amount is recovered?”
That change in perspective is one of the most valuable habits B9 can encourage. A small advance may solve a specific problem without disrupting the rest of the month. A larger request may feel reassuring today but leave too little for regular obligations later. I would choose the smallest amount that solves the immediate issue, not the largest amount the process makes available.
For a realistic example, imagine that my grocery budget is short shortly before payday and I need food for several days. I would first calculate the exact gap, request only what is necessary if the offer suits my situation, and then record the expected repayment in my budget. I would not use the advance for optional shopping simply because the money becomes visible in the account.
Managing the handoff to everyday spending
The app’s role does not end when money becomes available. The next handoff is from B9 to my normal banking and spending routine. I would move carefully here: confirm where the funds arrived, check the balance in my usual account, and avoid treating the advance as indistinguishable from regular wages. Keeping that mental separation makes repayment easier to plan.
This workflow is especially important for people who use several accounts. If bills leave one account while income arrives in another, I would note where the advance sits and where repayment is expected to come from. A simple calendar reminder or budget note can prevent the common error of spending the money and then being surprised when the next paycheck is smaller.
I also would not assume that an advance replaces a bank transfer, an emergency fund, or a conversation with a bill provider. Those alternatives can be better when they cost less, offer more time, or avoid reducing the next paycheck. B9 is strongest when the timing problem is temporary and the repayment impact is fully understood.
What the result feels like in practice
The main benefit is speed of decision-making around a short-term cash need. Instead of waiting passively for payday, I can use a dedicated finance app to explore whether an early-paycheck option fits the situation. That focus is clearer than opening a full banking app and searching through unrelated tools.
For me, the strongest practical feature is not simply access to money. It is the ability to connect an immediate request with the next income event. That connection encourages a more concrete question: what happens after payday? If I use the app with that question in mind, it becomes a planning aid as well as a transaction tool.
There is also a psychological advantage to having a defined workflow. I can identify the shortfall, review the request, check the repayment effect, and decide. That is more disciplined than relying on an overdraft or putting an urgent purchase on a credit card without knowing when the balance will be cleared. The benefit depends on my own restraint, but the structure helps.
Where the flow can break down
The first possible break is eligibility or availability. A person may install the app expecting an immediate advance and discover that the service cannot provide the requested outcome for their circumstances. That is not a reason to judge the app unfairly, but it is a reason not to build a bill payment plan around money that has not yet been approved.
The second break is incomplete or outdated information. If income details, account connections, or personal records do not line up, the setup may take longer than expected. I would keep relevant information close at hand and check spelling, account ownership, and current employment details before assuming the app is malfunctioning.
The third break is timing. Even when a request is accepted, “early” does not mean that money will necessarily solve an expense due within minutes. I would begin the process before an urgent deadline, not when a payment is already overdue. Anyone facing a same-day emergency should also contact the merchant, landlord, utility provider, or bank directly rather than relying on an unconfirmed advance.
Repayment is the most serious break point. If the next paycheck is already committed to rent, debt, childcare, or utilities, taking an advance can simply move the stress forward. In that case I would prefer negotiating a payment date, using savings, or choosing a lower-cost alternative where available. B9 is not the right tool when the underlying problem is a persistent lack of income.
How it compares with familiar alternatives
Compared with an overdraft, an early-paycheck app can feel more deliberate because I am requesting a defined advance instead of allowing an account to fall below zero. The trade-off is that I must complete a separate setup and understand the service’s terms. An overdraft may appear automatically, but that convenience can make its consequences easier to overlook.
Compared with a credit card, B9 is more closely tied to incoming pay rather than an open revolving balance. That can make the repayment horizon easier to visualize. A credit card may still be better for a purchase that can be repaid gradually, especially if its terms are already familiar and more favorable. I would not use either option without comparing the total cost and timing.
Compared with a traditional personal loan, the app is aimed at a much narrower need: bridging income timing rather than financing a large planned expense. A bank loan may offer a clearer long-term structure for a substantial purchase, while B9 makes more sense for a short-lived gap. Using a paycheck advance for a large, ongoing obligation would be a mismatch.
Compared with a savings buffer, there is no contest when savings are available and using them does not create another problem. Savings avoid the need to arrange an advance and do not reduce the next paycheck. My practical order would be: use a realistic emergency fund first, ask for flexibility from the biller second, and consider an advance only after checking its full effect.
Who will get the most from B9
I think the app is best suited to someone with predictable incoming pay who occasionally faces a timing mismatch. That person should be able to identify the exact amount needed, understand the next payday’s obligations, and repay without depending on another advance immediately afterward.
It may also suit users who prefer a focused mobile workflow over calling a bank or managing a credit product. The free entry point and simple purpose make it approachable for someone exploring early-paycheck services for the first time. The current release is version 3.59.0 and supports devices running Android 8.0 or later, so compatibility is worth checking before planning around it.
I would tell a friend to skip it if their income is irregular, their account is already under pressure, or they are hoping an advance will cover a long-term budget shortfall. I would also hesitate if they dislike connecting financial information to an app or are unlikely to track the repayment date. In those cases, a conversation with a bank, employer, creditor, or financial counselor may be more appropriate.
Small habits that make the workflow safer
- Request the smallest useful amount: work backward from the bill or purchase instead of starting with the maximum visible offer.
- Budget the repayment first: write down what the next paycheck must cover before spending the advance.
- Keep a separate record: note the request date, expected repayment, and account involved so the transaction does not disappear among normal spending.
- Prepare a backup: if the need is urgent, have another plan rather than assuming approval or delivery will happen in time.
- Reassess repeated use: needing advances every pay cycle is a signal to review expenses, income, and recurring bills rather than simply repeating the same action.
My final view after following the complete path
B9: Cash Advance is a focused finance app for a focused problem: getting access to part of a paycheck before the usual payday. I like that its purpose is easy to understand and that the workflow can encourage users to connect today’s need with tomorrow’s repayment. The fact that it is free to install and has attracted over one million installs makes it easy for interested users to investigate.
My recommendation comes with a firm condition: use it as a short-term timing bridge, not as an extension of income. Read every offer screen, check the effect on the next paycheck, and keep an alternative plan for urgent bills. The 3.9 average from around twelve thousand ratings reflects a product that clearly works for many people while leaving room for uneven experiences, particularly around setup, eligibility, and personal financial fit.
For someone with steady pay and a temporary gap, I can see the value. For someone already borrowing to cover ordinary living costs, I would recommend stepping back before using it. The best outcome is not receiving money early; it is solving the immediate problem without creating a larger one on payday.
FAQs for B9: Cash Advance
01What is B9: Cash Advance and how does it work?
B9: Cash Advance is a financial app that offers users the ability to access a portion of their paycheck before their actual payday. It works by linking to your bank account to verify employment and income, allowing you to request an advance based on your earnings. This can help you manage unexpected expenses without waiting for your paycheck.
02Is B9: Cash Advance safe to use and how is my data protected?
Yes, B9: Cash Advance is designed with security in mind. It uses bank-level encryption to protect your personal and financial information. The app does not store sensitive data on your device, and its privacy policy ensures that your information is not shared with third parties without your consent.
03Are there any fees associated with using B9: Cash Advance?
B9: Cash Advance typically does not charge interest on the cash advances you receive. However, there may be a small membership fee or optional tips that you can provide for the service. It's important to review the terms and conditions within the app to understand any potential costs.
04How quickly can I receive a cash advance through B9?
Once your account is set up and verified, you can typically receive a cash advance within a few hours to a day. The timing may vary based on your bank’s processing times. For the fastest service, ensure that you have a stable internet connection and that your bank account details are correct.
05What are the eligibility requirements for using B9: Cash Advance?
To be eligible for B9: Cash Advance, you must have a consistent source of income and a bank account where your paychecks are direct-deposited. The app may require verification of employment and income levels to determine how much you can advance. Ensure all your financial details are accurate for a smooth setup.
Pros
- Easy and quick cash advances.
- No credit check required.
- User-friendly interface.
- Fast approval process.
- Transparent fee structure.
Cons
- High interest rates.
- Limited to small cash amounts.
- May encourage dependency.
- Requires bank account access.
- Fees for late repayment.

B9: Cash Advance
Gallery